Temps are dropping, the leaves are turning and you know what that means: Fall is here, which is the best time to prepare your house for the chill that follows. But we all know that keeping warm takes energy and, yes, is costly. Here are…
⏱ 3 min read
Temps are dropping, the leaves are turning, and you know what that means: Fall is here, which is the best time to prepare your house for the chill that follows. But we all know that keeping warm takes energy and, yes, is costly. Here are a few easy ways to conserve.
Fix stuff around your house. These are simple and might require a little elbow grease on your part, but they’re well worth it because they help your house stay warmer, eliminate drafts, and help your heater work more efficiently.
Seal gaps around your windows and doors with caulk or weatherstripping.
Close fireplace dampers when you’re not using them.
Replace HVAC filters. For your furnace, this should be done one to three months before cold weather hits. It helps improve air quality (and air flow) inside your home.
Add door sweeps to exterior doors.
Reverse your ceiling fans; set them to clockwise and put them on a low setting to push the warm air down into the room.
Hang thick(er) curtains so heat doesn’t seep out.
Make sure vents and returns aren’t blocked by furniture or rugs.
Check your heating system. Before the Arctic blast arrives, these tasks are key:
Schedule an HVAC inspection – aka a tune-up.
Install a programmable or smart thermostat.
Lower your thermostat by 7-10 degrees when you’re away.
Look at your insulation. These chores might require you to hire someone.
Add attic insulation if your house is under-insulated so you can reduce your heating costs and keep your house toasty. (In fact, poor insulation is one of the biggest sources of energy loss.)
Insulate pipes that are exposed, as well as your water heater.
Seal and insulate all your ductwork in your attic, garage, and crawl spaces.
Inspect your water heater. Making sure you have warm water in the cooler months is critical. You’ll be quite happy not having to take cold showers, as well as not expending as much energy.
Lower your water heater temperature to 120°F.
Install low-flow showerheads.
Fix dripping faucets immediately.
Examine the exterior of your house. Even the outside of your home needs attention.
Clean gutters and downspouts to prevent ice dams, moisture problems, and foundation issues.
Trim branches that could block winter sunlight from south-facing windows.
Check for cracks where utilities enter the house and seal them.
Check your roof, too, for signs of wear or damage.
Test your heating system early. Put this on your calendar! Don’t wait until it’s a tundra outside to turn on your furnace or heat pump.
If you need repairs, schedule maintenance before HVAC companies get all booked up.
Check your smoke and carbon monoxide detectors. Don’t leave this unattended!
Replace batteries if needed and test them all. You want to make sure your family’s safe during the upcoming heating season.
Even though fall is upon us, know this: Winter is coming, as the show famously claims. You can never be too prepared!
How to Save Energy This Fall
October 1, 2026 · Blog, Tip of the Month, Uncategorized
⏱ 3 min read
Temps are dropping, the leaves are turning, and you know what that means: Fall is here, which is the best time to prepare your house for the chill that follows. But we all know that keeping warm takes energy and, yes, is costly. Here are a few easy ways to conserve.
Fix stuff around your house. These are simple and might require a little elbow grease on your part, but they’re well worth it because they help your house stay warmer, eliminate drafts, and help your heater work more efficiently.
Seal gaps around your windows and doors with caulk or weatherstripping.
Close fireplace dampers when you’re not using them.
Replace HVAC filters. For your furnace, this should be done one to three months before cold weather hits. It helps improve air quality (and air flow) inside your home.
Add door sweeps to exterior doors.
Reverse your ceiling fans; set them to clockwise and put them on a low setting to push the warm air down into the room.
Hang thick(er) curtains so heat doesn’t seep out.
Make sure vents and returns aren’t blocked by furniture or rugs.
Check your heating system. Before the Arctic blast arrives, these tasks are key:
Schedule an HVAC inspection – aka a tune-up.
Install a programmable or smart thermostat.
Lower your thermostat by 7-10 degrees when you’re away.
Look at your insulation. These chores might require you to hire someone.
Add attic insulation if your house is under-insulated so you can reduce your heating costs and keep your house toasty. (In fact, poor insulation is one of the biggest sources of energy loss.)
Insulate pipes that are exposed, as well as your water heater.
Seal and insulate all your ductwork in your attic, garage, and crawl spaces.
Inspect your water heater. Making sure you have warm water in the cooler months is critical. You’ll be quite happy not having to take cold showers, as well as not expending as much energy.
Lower your water heater temperature to 120°F.
Install low-flow showerheads.
Fix dripping faucets immediately.
Examine the exterior of your house. Even the outside of your home needs attention.
Clean gutters and downspouts to prevent ice dams, moisture problems, and foundation issues.
Trim branches that could block winter sunlight from south-facing windows.
Check for cracks where utilities enter the house and seal them.
Check your roof, too, for signs of wear or damage.
Test your heating system early. Put this on your calendar! Don’t wait until it’s a tundra outside to turn on your furnace or heat pump.
If you need repairs, schedule maintenance before HVAC companies get all booked up.
Check your smoke and carbon monoxide detectors. Don’t leave this unattended!
Replace batteries if needed and test them all. You want to make sure your family’s safe during the upcoming heating season.
Even though fall is upon us, know this: Winter is coming, as the show famously claims. You can never be too prepared!
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
The purpose of estate planning is to distribute your assets to heirs in a formal, legal process. If you do not have any heirs to speak of, you might not feel the need to do this. However, your assets will go somewhere, so you may…
⏱ 6 min read
The purpose of estate planning is to distribute your assets to heirs in a formal, legal process. If you do not have any heirs to speak of, you might not feel the need to do this. However, your assets will go somewhere, so you may want to have control over that before the state steps in to decide for you.
Without a formal will, the general rule for inheritance distribution starts with a surviving spouse and children (who often share the estate), followed by grandchildren, parents, siblings, nephews and nieces, grandparents, then other extended relatives such as aunts, uncles and cousins. The exact order varies by state. Note that ex-spouses, and in most states stepchildren, receive nothing under standard state inheritance laws; they must be specified in a will or trust document, or named as an account beneficiary, to receive any consideration.
This means that, without a will or close family heir, your assets could go to an estranged sibling or even a cousin you’ve never met. If you have absolutely no family left when you pass on, the proceeds generally go to the state through a process called escheat (this includes funds from physical assets that are auctioned off).
Start with Living Matters
Before you start allocating where your assets go after your death, first complete paperwork assigning people to manage your assets if you ever become incapacitated while still alive. The key documents include:
Durable Power of Attorney (DPOA) – this document names an agent, such as a trusted friend, attorney, or bank trust department, to take over managing your financial and legal affairs if you are deemed unable.
Health Care Directive – authorizes someone to make medical decisions on your behalf when you are unable.
Living Will – details what life-saving procedures and treatments you would and would not like to receive in order to keep you alive. Separately, a DNR (do not resuscitate) order, signed by your physician, directs medical staff not to perform CPR if your heart or breathing stops.
Choose Your Estate Manager
Your will should assign an executor to manage your estate once you pass away. Again, this can be a friend or a custodian (e.g., bank, attorney, financial advisor). This person is responsible for initiating probate court proceedings and distributing assets as dictated by your will. Responsibilities may include notifying your landlord/lender(s), utility providers, banks, credit card companies, investments, and insurance companies of your passing, as well as managing the sale of any property you own. Most states allow any competent adult to serve as executor, including the attorney who drafted your will, though some states restrict people with felony convictions or those who live out of state.
It behooves the heirless to consider estate planning to better allocate funds toward people or causes they care about, such as friends, coworkers, or charities. For example:
Animal shelter or humane society
Local church or other religious institution
The public library
The Public Broadcasting Service (PBS)
A local land trust, the World Wildlife Fund or other conservation organizations
A favorite city institution, such as a museum, zoo, symphony, ballet or theater
Scholarship fund for your alma mater – K-12 or university
YMCA or Jewish community center
Medical institutions, such as local clinics, St. Jude Children’s Research Hospital, Planned Parenthood, cancer or other disease research
Charities for children, such as the National Center for Missing & Exploited Children or Children’s Health Fund
If nothing local appeals, browse options at websites such as CharityWatch.org, a website dedicated to assessing how efficiently charities use donations.
Note that retirement accounts and life insurance policies generally request a beneficiary, and many bank and brokerage accounts allow one. You may not even remember that when you opened an account years ago, you listed your boyfriend or wife at the time as your beneficiary, even though that person is now your ex. Be aware that these beneficiary designations supersede any will instructions. These assets pass directly to the named beneficiary outside of probate, without going through your executor. Be sure to check and confirm your beneficiary designations while you are still alive to eliminate this issue. Many states automatically revoke an ex-spouse’s designation after a divorce, but that rule generally does not apply to employer retirement plans such as 401(k)s, so an ex could still collect. If no beneficiary is named, the account typically becomes part of your estate and goes through probate.
Charitable Donations
For people with substantial assets who want to leave money to one or more charities, sophisticated philanthropic vehicles include:
Charitable remainder trust – The money is deposited into a trust while you are still alive. You receive an immediate tax deduction based on the present value of the charity’s future share (the remainder interest) of this irrevocable trust, as well as an income stream from the trust for life or for a set term of up to 20 years. When the trust ends, whatever charity you designate receives the remaining assets.
Donor-advised funds – You make an irrevocable, tax-deductible contribution of cash, securities, or appreciated noncash assets to a fund, which is professionally managed for future growth. You may recommend money be granted to a qualified 501(c)(3) charity over time, basically leaving a legacy that continues to give.
Private foundations – You can actually start your own charitable organization with an initial tax-deductible gift and appoint a board of directors or trustees (who may receive reasonable compensation) to manage and distribute assets according to your wishes. Foundations can make grants beyond public charities in limited cases, but only under strict IRS rules. They must also distribute at least 5 percent of their assets each year and pay an excise tax on investment income, and donors face lower deduction limits than for gifts to public charities.
It is best to consult with a financial advisor, tax professional, or estate planning attorney with experience in setting up a sophisticated charitable giving plan to make the most of your contributions.
Heirless Estate Planning
October 1, 2026 · Blog, Financial Planning, Uncategorized
⏱ 6 min read
The purpose of estate planning is to distribute your assets to heirs in a formal, legal process. If you do not have any heirs to speak of, you might not feel the need to do this. However, your assets will go somewhere, so you may want to have control over that before the state steps in to decide for you.
Without a formal will, the general rule for inheritance distribution starts with a surviving spouse and children (who often share the estate), followed by grandchildren, parents, siblings, nephews and nieces, grandparents, then other extended relatives such as aunts, uncles and cousins. The exact order varies by state. Note that ex-spouses, and in most states stepchildren, receive nothing under standard state inheritance laws; they must be specified in a will or trust document, or named as an account beneficiary, to receive any consideration.
This means that, without a will or close family heir, your assets could go to an estranged sibling or even a cousin you’ve never met. If you have absolutely no family left when you pass on, the proceeds generally go to the state through a process called escheat (this includes funds from physical assets that are auctioned off).
Start with Living Matters
Before you start allocating where your assets go after your death, first complete paperwork assigning people to manage your assets if you ever become incapacitated while still alive. The key documents include:
Durable Power of Attorney (DPOA) – this document names an agent, such as a trusted friend, attorney, or bank trust department, to take over managing your financial and legal affairs if you are deemed unable.
Health Care Directive – authorizes someone to make medical decisions on your behalf when you are unable.
Living Will – details what life-saving procedures and treatments you would and would not like to receive in order to keep you alive. Separately, a DNR (do not resuscitate) order, signed by your physician, directs medical staff not to perform CPR if your heart or breathing stops.
Choose Your Estate Manager
Your will should assign an executor to manage your estate once you pass away. Again, this can be a friend or a custodian (e.g., bank, attorney, financial advisor). This person is responsible for initiating probate court proceedings and distributing assets as dictated by your will. Responsibilities may include notifying your landlord/lender(s), utility providers, banks, credit card companies, investments, and insurance companies of your passing, as well as managing the sale of any property you own. Most states allow any competent adult to serve as executor, including the attorney who drafted your will, though some states restrict people with felony convictions or those who live out of state.
It behooves the heirless to consider estate planning to better allocate funds toward people or causes they care about, such as friends, coworkers, or charities. For example:
Animal shelter or humane society
Local church or other religious institution
The public library
The Public Broadcasting Service (PBS)
A local land trust, the World Wildlife Fund or other conservation organizations
A favorite city institution, such as a museum, zoo, symphony, ballet or theater
Scholarship fund for your alma mater – K-12 or university
YMCA or Jewish community center
Medical institutions, such as local clinics, St. Jude Children’s Research Hospital, Planned Parenthood, cancer or other disease research
Charities for children, such as the National Center for Missing & Exploited Children or Children’s Health Fund
If nothing local appeals, browse options at websites such as CharityWatch.org, a website dedicated to assessing how efficiently charities use donations.
Note that retirement accounts and life insurance policies generally request a beneficiary, and many bank and brokerage accounts allow one. You may not even remember that when you opened an account years ago, you listed your boyfriend or wife at the time as your beneficiary, even though that person is now your ex. Be aware that these beneficiary designations supersede any will instructions. These assets pass directly to the named beneficiary outside of probate, without going through your executor. Be sure to check and confirm your beneficiary designations while you are still alive to eliminate this issue. Many states automatically revoke an ex-spouse’s designation after a divorce, but that rule generally does not apply to employer retirement plans such as 401(k)s, so an ex could still collect. If no beneficiary is named, the account typically becomes part of your estate and goes through probate.
Charitable Donations
For people with substantial assets who want to leave money to one or more charities, sophisticated philanthropic vehicles include:
Charitable remainder trust – The money is deposited into a trust while you are still alive. You receive an immediate tax deduction based on the present value of the charity’s future share (the remainder interest) of this irrevocable trust, as well as an income stream from the trust for life or for a set term of up to 20 years. When the trust ends, whatever charity you designate receives the remaining assets.
Donor-advised funds – You make an irrevocable, tax-deductible contribution of cash, securities, or appreciated noncash assets to a fund, which is professionally managed for future growth. You may recommend money be granted to a qualified 501(c)(3) charity over time, basically leaving a legacy that continues to give.
Private foundations – You can actually start your own charitable organization with an initial tax-deductible gift and appoint a board of directors or trustees (who may receive reasonable compensation) to manage and distribute assets according to your wishes. Foundations can make grants beyond public charities in limited cases, but only under strict IRS rules. They must also distribute at least 5 percent of their assets each year and pay an excise tax on investment income, and donors face lower deduction limits than for gifts to public charities.
It is best to consult with a financial advisor, tax professional, or estate planning attorney with experience in setting up a sophisticated charitable giving plan to make the most of your contributions.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
According to FitchRatings, over the past 12 months ending August 2026, there were 109 defaults by 89 entities, compared to the same period ending July 2026 where 83 entities saw 105 defaults. With businesses (especially life insurers) exposed to asset…
⏱ 3 min read
According to Fitch Ratings, over the past 12 months ending August 2026, there were 109 defaults by 89 entities, compared to the same period ending July 2026, when 83 entities saw 105 defaults. With businesses (especially life insurers) exposed to asset management risks, it’s important to understand how to find financial balance.
Defining Asset Valuation Reserve (AVR)
An AVR is a repository for life insurance companies to offset a drop in markets and/or asset portfolios that are meant to fulfill contractual obligations for claims, annuities, and related insurance obligations.
According to the American Council of Life Insurers and the National Association of Insurance Commissioners (NAIC), the AVR factors in every realized investment profit and loss after factoring in net deferred taxes for credit and equity investments. Companies are required to fund the AVR initially and adjust it annually to manage ongoing and future obligations.
As part of the agreement that insurance companies have to pay out an insurance claim in exchange for receiving premiums, an insurance company has to ensure they are financially solvent to keep paying out claims. The same requirement also pertains to annuities that an insurance company contracts with customers, including making periodic payments. Through the valuation reserve requirements, insurance companies can measure their reserves and investments to increase the chance they’ll be able to meet their financial obligations regularly.
Depending on the interest rate environment, insurance companies can experience threats to their allocated reserves to continue annuity payments over time compared to life benefits paid out all at once. Based on the American Council of Life Insurers, the percentage in reserves for annuities increased to 23 percent in 1990, up from 8 percent in 1980, showing how insurers must keep up with client demands and manage risk.
How it’s Constructed
An AVR creates an organized set of entries for the assets and liabilities. Insurance companies are also able to compare assets and liabilities against actuarial valuation standards to plan for projected unknown, unsettled asset shortfalls. It also helps companies monitor the appropriate detection of long-term anticipated stock investment proceeds. For publicly traded insurance companies, it provides greater transparency for equity and bond holders, along with regulators.
The default component accounts for four-fifths of the AVR. Insurance companies implement investment vehicles such as mortgages and fixed-income options to manage their credit risk. As the name implies, the equity piece of the AVR balances the reserve with preferred and common equities or stocks, along with real estate investments. This mix is required for insurance companies because it creates a buffer from gains realized from positive market years, which offset insurance company obligations during periods of negative market performance.
Building the AVR is unique to each company’s financial makeup and needs to be dynamic, but must follow industry standards. While insurers or any market participant cannot predict the market with 100 percent accuracy, insurers with a properly constructed and reported AVR can more easily navigate an economy that becomes turbulent and uncertain.
October 1, 2026 · Blog, General Business News, Uncategorized
⏱ 3 min read
According to Fitch Ratings, over the past 12 months ending August 2026, there were 109 defaults by 89 entities, compared to the same period ending July 2026, when 83 entities saw 105 defaults. With businesses (especially life insurers) exposed to asset management risks, it’s important to understand how to find financial balance.
Defining Asset Valuation Reserve (AVR)
An AVR is a repository for life insurance companies to offset a drop in markets and/or asset portfolios that are meant to fulfill contractual obligations for claims, annuities, and related insurance obligations.
According to the American Council of Life Insurers and the National Association of Insurance Commissioners (NAIC), the AVR factors in every realized investment profit and loss after factoring in net deferred taxes for credit and equity investments. Companies are required to fund the AVR initially and adjust it annually to manage ongoing and future obligations.
As part of the agreement that insurance companies have to pay out an insurance claim in exchange for receiving premiums, an insurance company has to ensure they are financially solvent to keep paying out claims. The same requirement also pertains to annuities that an insurance company contracts with customers, including making periodic payments. Through the valuation reserve requirements, insurance companies can measure their reserves and investments to increase the chance they’ll be able to meet their financial obligations regularly.
Depending on the interest rate environment, insurance companies can experience threats to their allocated reserves to continue annuity payments over time compared to life benefits paid out all at once. Based on the American Council of Life Insurers, the percentage in reserves for annuities increased to 23 percent in 1990, up from 8 percent in 1980, showing how insurers must keep up with client demands and manage risk.
How it’s Constructed
An AVR creates an organized set of entries for the assets and liabilities. Insurance companies are also able to compare assets and liabilities against actuarial valuation standards to plan for projected unknown, unsettled asset shortfalls. It also helps companies monitor the appropriate detection of long-term anticipated stock investment proceeds. For publicly traded insurance companies, it provides greater transparency for equity and bond holders, along with regulators.
The default component accounts for four-fifths of the AVR. Insurance companies implement investment vehicles such as mortgages and fixed-income options to manage their credit risk. As the name implies, the equity piece of the AVR balances the reserve with preferred and common equities or stocks, along with real estate investments. This mix is required for insurance companies because it creates a buffer from gains realized from positive market years, which offset insurance company obligations during periods of negative market performance.
Building the AVR is unique to each company’s financial makeup and needs to be dynamic, but must follow industry standards. While insurers or any market participant cannot predict the market with 100 percent accuracy, insurers with a properly constructed and reported AVR can more easily navigate an economy that becomes turbulent and uncertain.
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Anyone who has moved retirement money out of an old employer’s plan knows how frustrating it can be. Every administrator has their own forms. Timelines are all over the place. Paper checks show up weeks later…
⏱ 4 min read
Anyone who has moved retirement money out of an old employer’s plan knows how frustrating it can be. Every administrator has their own forms. Timelines are all over the place. Paper checks show up weeks later with vague instructions. The whole thing should have been fixed a long time ago.
The IRS is finally doing something about it. Notice 2026-49 puts out four sample forms and a five-step procedure meant to bring some consistency to direct rollovers. Plans do not have to use them, and there is no safe harbor, but you can see where this is going.
The Problem Worth Solving
When you leave a job, you have to figure out what to do with your 401(k). You can cash it out and take the tax hit. You can leave it sitting there. Or you can roll it into a new employer’s plan or an IRA.
A direct rollover is usually the way to go. The money travels straight from the old plan to the new one without ever hitting your bank account, which keeps things clean and avoids the 60-day deadline you face if you take possession yourself.
The trouble is that every plan does things differently. A 2024 GAO study found that roughly one in three people doing rollovers ended up with a paper check in hand that they were supposed to forward themselves. Checks get lost. They sit on the counter for weeks. And the whole time, that money is not invested anywhere.
How the New System Works
Here is what Treasury is proposing. You fill out Form 1 and give it to the plan or IRA that will be receiving your money. That form lets the receiving plan reach out to your old plan and handle the transfer on your behalf. The two plans swap Forms 2 through 4 to make sure everything is in order. If something goes sideways, the receiving plan has to tell you.
The IRS wants this done electronically whenever possible. When electronic is not an option, the old plan should write a check payable to the receiving plan for your benefit and mail it directly there. No more sending checks to participants and hoping they take it from there.
Tax Rules Stay the Same
None of this changes how rollovers are taxed. Eligible distributions that complete a proper rollover still stay out of income. You still cannot roll over a required minimum distribution. Pre-tax money stays pre-tax. Roth stays Roth. This is about the plumbing, not the tax code.
IRA-to-IRA transfers are not covered here. Those already go through the ACATS electronic system, so Treasury left them alone.
No Safe Harbor Yet
Plans can use these forms, change them, or ignore them completely. Right now, there is no reward for following along.
That could change. Treasury says it is thinking about offering safe harbors down the road. A receiving plan that uses the standard forms might eventually be allowed to assume the rollover is valid unless something looks off. That would give administrators a real incentive to adopt the new process.
Conclusion and What Comes Next
The IRS has hinted at bigger changes. Future guidance might require electronic transfers across the board, kill off the practice of mailing checks to participants, and get rid of some of the procedural friction that slows things down.
For now, the sample forms are sitting in the appendix of Notice 2026-49. They are there if you want them. If you have ever spent weeks tracking down a check that went to the wrong address or trying to explain one plan’s process to another plan’s administrator, you understand what Treasury is trying to fix. They want rollovers to be faster, simpler, and harder to mess up. This is a start.
Rolling Over Your 401(k) Just Got Less Painful – Here’s What the IRS Changed
October 1, 2026 · Blog, Tax and Financial News, Uncategorized
⏱ 4 min read
Anyone who has moved retirement money out of an old employer’s plan knows how frustrating it can be. Every administrator has their own forms. Timelines are all over the place. Paper checks show up weeks later with vague instructions. The whole thing should have been fixed a long time ago.
The IRS is finally doing something about it. Notice 2026-49 puts out four sample forms and a five-step procedure meant to bring some consistency to direct rollovers. Plans do not have to use them, and there is no safe harbor, but you can see where this is going.
The Problem Worth Solving
When you leave a job, you have to figure out what to do with your 401(k). You can cash it out and take the tax hit. You can leave it sitting there. Or you can roll it into a new employer’s plan or an IRA.
A direct rollover is usually the way to go. The money travels straight from the old plan to the new one without ever hitting your bank account, which keeps things clean and avoids the 60-day deadline you face if you take possession yourself.
The trouble is that every plan does things differently. A 2024 GAO study found that roughly one in three people doing rollovers ended up with a paper check in hand that they were supposed to forward themselves. Checks get lost. They sit on the counter for weeks. And the whole time, that money is not invested anywhere.
How the New System Works
Here is what Treasury is proposing. You fill out Form 1 and give it to the plan or IRA that will be receiving your money. That form lets the receiving plan reach out to your old plan and handle the transfer on your behalf. The two plans swap Forms 2 through 4 to make sure everything is in order. If something goes sideways, the receiving plan has to tell you.
The IRS wants this done electronically whenever possible. When electronic is not an option, the old plan should write a check payable to the receiving plan for your benefit and mail it directly there. No more sending checks to participants and hoping they take it from there.
Tax Rules Stay the Same
None of this changes how rollovers are taxed. Eligible distributions that complete a proper rollover still stay out of income. You still cannot roll over a required minimum distribution. Pre-tax money stays pre-tax. Roth stays Roth. This is about the plumbing, not the tax code.
IRA-to-IRA transfers are not covered here. Those already go through the ACATS electronic system, so Treasury left them alone.
No Safe Harbor Yet
Plans can use these forms, change them, or ignore them completely. Right now, there is no reward for following along.
That could change. Treasury says it is thinking about offering safe harbors down the road. A receiving plan that uses the standard forms might eventually be allowed to assume the rollover is valid unless something looks off. That would give administrators a real incentive to adopt the new process.
Conclusion and What Comes Next
The IRS has hinted at bigger changes. Future guidance might require electronic transfers across the board, kill off the practice of mailing checks to participants, and get rid of some of the procedural friction that slows things down.
For now, the sample forms are sitting in the appendix of Notice 2026-49. They are there if you want them. If you have ever spent weeks tracking down a check that went to the wrong address or trying to explain one plan’s process to another plan’s administrator, you understand what Treasury is trying to fix. They want rollovers to be faster, simpler, and harder to mess up. This is a start.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
With over $4 trillion in merger and acquisition transactions happening in 2025, understanding the necessary accounting considerations is essential to see how tax professionals can navigate…
⏱ 3 min read
With over $4 trillion in merger and acquisition transactions happening in 2025, understanding the necessary accounting considerations is essential to see how tax professionals can navigate financial statements.
Defining Bolt-On Acquisitions
This process is often used by private equity companies and occurs when a bigger business acquires a smaller company, providing investors with synergistic performance. This happens because the smaller company gives the bigger company a faster edge through complementary services, products or geographical advantages without having to do research and development from scratch. It also provides the acquiring business with new market access, further increasing the value of an acquisition for the acquiring company.
Bolt-On Versus Tuck-In Acquisitions
Bolt-on companies still have some level of autonomy and keep some of their unique brand identity post-acquisition, despite the acquired assets being integrated into the acquiring company’s overall structure. This contrasts with tuck-in acquisitions, where this type of acquisition completely absorbs the entire assets of the acquired company into the acquiring company.
Defining Asset Acquisition & Accounting Treatment
FASB’s Accounting Standards Codification Topic 805, Business Combinations, further defines asset acquisitions, including bolt-on acquisitions.
Asset acquisitions are defined as the complete fair value of the acquired assets as defined by similarly identifiable attributes. By meeting the so-called “screen test,” ASC 805 defines it as an asset acquisition. Based upon this type of transaction, acquirers are required to account for it via ASC 805-50’s cost model.
Transaction expenses, including immediately attributable and additive expenses the company sees during the asset acquisition period, are factored into the purchased asset(s) costs. This lowers expenses during the acquisition’s time frame compared to a business combination, which results in greater depreciation expenses over the acquired asset’s life.
Another consideration for asset acquisitions is failing to recognize goodwill. Assets could have a higher basis that’s subject to depreciation or amortization if the value is reported higher than the asset’s fair value. Similarly, when it comes to ASC 842-10-35-3, unless the lease is materially changed, the acquirer must maintain the acquiree’s same lease circumstances.
Defining Business Acquisition
ASC 805 defines a business as a functional combination of assets and processes, featuring novel methods for developing significant input, in order to create new outcomes. This is a subjective process that ASC 805 describes in depth and often requires expertise to make a judgment call. According to ASC 805-10, accounting considerations for business combinations include measuring liabilities and assets at fair value. Legal and consulting transaction costs beginning with the acquisition preparation through the acquisition date should be expensed.
Goodwill is recognized as an asset and evaluated once a year for impairment. Like an asset acquisition, lease classification is kept the same as the acquired company, unless the lease agreement has material alterations.
Conclusion
While there are many different types of acquisition considerations and relevant procedures required, understanding how to navigate bolt-on acquisitions is essential to make the most of accounting for mergers and acquisitions in 2026 and beyond.
How to Account for Bolt-On Acquisitions
August 1, 2026 · Accounting News, Blog, Uncategorized
⏱ 3 min read
With over $4 trillion in merger and acquisition transactions happening in 2025, understanding the necessary accounting considerations is essential to see how tax professionals can navigate financial statements.
Defining Bolt-On Acquisitions
This process is often used by private equity companies and occurs when a bigger business acquires a smaller company, providing investors with synergistic performance. This happens because the smaller company gives the bigger company a faster edge through complementary services, products or geographical advantages without having to do research and development from scratch. It also provides the acquiring business with new market access, further increasing the value of an acquisition for the acquiring company.
Bolt-On Versus Tuck-In Acquisitions
Bolt-on companies still have some level of autonomy and keep some of their unique brand identity post-acquisition, despite the acquired assets being integrated into the acquiring company’s overall structure. This contrasts with tuck-in acquisitions, where this type of acquisition completely absorbs the entire assets of the acquired company into the acquiring company.
Defining Asset Acquisition & Accounting Treatment
FASB’s Accounting Standards Codification Topic 805, Business Combinations, further defines asset acquisitions, including bolt-on acquisitions.
Asset acquisitions are defined as the complete fair value of the acquired assets as defined by similarly identifiable attributes. By meeting the so-called “screen test,” ASC 805 defines it as an asset acquisition. Based upon this type of transaction, acquirers are required to account for it via ASC 805-50’s cost model.
Transaction expenses, including immediately attributable and additive expenses the company sees during the asset acquisition period, are factored into the purchased asset(s) costs. This lowers expenses during the acquisition’s time frame compared to a business combination, which results in greater depreciation expenses over the acquired asset’s life.
Another consideration for asset acquisitions is failing to recognize goodwill. Assets could have a higher basis that’s subject to depreciation or amortization if the value is reported higher than the asset’s fair value. Similarly, when it comes to ASC 842-10-35-3, unless the lease is materially changed, the acquirer must maintain the acquiree’s same lease circumstances.
Defining Business Acquisition
ASC 805 defines a business as a functional combination of assets and processes, featuring novel methods for developing significant input, in order to create new outcomes. This is a subjective process that ASC 805 describes in depth and often requires expertise to make a judgment call. According to ASC 805-10, accounting considerations for business combinations include measuring liabilities and assets at fair value. Legal and consulting transaction costs beginning with the acquisition preparation through the acquisition date should be expensed.
Goodwill is recognized as an asset and evaluated once a year for impairment. Like an asset acquisition, lease classification is kept the same as the acquired company, unless the lease agreement has material alterations.
Conclusion
While there are many different types of acquisition considerations and relevant procedures required, understanding how to navigate bolt-on acquisitions is essential to make the most of accounting for mergers and acquisitions in 2026 and beyond.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Sunshine Protection Act of 2025 (HR 139) – The purpose of this legislation is to make daylight savings time (DST) permanent for most of the country. States…
⏱ 3 min read
Sunshine Protection Act of 2025 (HR 139) – The purpose of this legislation is to make daylight savings time (DST) permanent for most of the country. States and territories presently exempt from DST may choose the standard time for those areas. This latest version of the bill was introduced by Rep. Vern Buchanan (R-FL) on Jan. 3, 2025. The Act passed in the House on July 14 and faces a mix of cross-aisle opposition and support in the Senate.
Lulu’s Law (S 1003) – Introduced on March 12, 2025, by Sen. Katie Britt (R-AL), this Act authorizes the Federal Communications Commission (FCC) to issue emergency alerts to mobile phones in the event of a shark attack (similar to other alerts, such as severe weather, missing children, etc.). The bill passed in the Senate on July 8, 2025, in the House on May 20 and was signed into law on June 26.
Artist Act (S 254) – The Artist Act amends the Marine Mammal Protection Act of 1972 by prohibiting states from imposing bans specifically on Alaska Native handicrafts and marine mammal ivory products. The bill is designed to protect the cultural practices and livelihood of Native American artists that create handicrafts and clothing using marine mammal ivory, bone or baleen. Introduced by Sen. Dan Sullivan (R-AK) on Jan. 24, 2025, the bill passed in the Senate on Oct. 8, 2025, and in the House on June 3. It was enacted by the president on June 12.
A bill to amend chapters 83 and 84 of title 5, United States Code, to authorize an increase of the retirement age for members of the Capitol Police (S 4530) – Prior to this amendment, members of the Capitol Police were required to retire either at age 57 or, if older than 57, upon completing 20 years of service. A previous waiver enabled officers to continue working until age 60. This bill increases the retirement age to between ages 57 and 62, when such a waiver is in the public interest. The bipartisan bill was introduced by Sen. Mitch McConnell (R-KY) on May 14. It passed in the Senate on May 15, the House on May 19, and became law on May 29.
American Access to Banking Act (HR 4544) – This law is designed to increase the number of community banks by making it easier to start them. Introduced by Rep. Maxine Waters (D-CA) on July 17, 2025, it passed 405-4 in the House on May 20 and is currently under consideration in the Senate.
Community Bank Deposit Access Act of 2025 (HR 5317) – This bill would create exemptions to FDIC rules that allow banks greater flexibility in funding loans. Specifically, the Act would alter how certain types of deposits are treated so they are no longer classified as brokered deposits. The legislation was introduced by Rep. French Hill (R-AR) on Sept. 11, 2025. It passed in the House on May 20 and currently resides in the Senate.
Extending Daylight Hours, Protecting Cultural Livelihoods and Making Local Banking Easier
August 1, 2026 · Blog, Congress at Work, Uncategorized
⏱ 3 min read
Sunshine Protection Act of 2025 (HR 139) – The purpose of this legislation is to make daylight savings time (DST) permanent for most of the country. States and territories presently exempt from DST may choose the standard time for those areas. This latest version of the bill was introduced by Rep. Vern Buchanan (R-FL) on Jan. 3, 2025. The Act passed in the House on July 14 and faces a mix of cross-aisle opposition and support in the Senate.
Lulu’s Law (S 1003) – Introduced on March 12, 2025, by Sen. Katie Britt (R-AL), this Act authorizes the Federal Communications Commission (FCC) to issue emergency alerts to mobile phones in the event of a shark attack (similar to other alerts, such as severe weather, missing children, etc.). The bill passed in the Senate on July 8, 2025, in the House on May 20 and was signed into law on June 26.
Artist Act (S 254) – The Artist Act amends the Marine Mammal Protection Act of 1972 by prohibiting states from imposing bans specifically on Alaska Native handicrafts and marine mammal ivory products. The bill is designed to protect the cultural practices and livelihood of Native American artists that create handicrafts and clothing using marine mammal ivory, bone or baleen. Introduced by Sen. Dan Sullivan (R-AK) on Jan. 24, 2025, the bill passed in the Senate on Oct. 8, 2025, and in the House on June 3. It was enacted by the president on June 12.
A bill to amend chapters 83 and 84 of title 5, United States Code, to authorize an increase of the retirement age for members of the Capitol Police (S 4530) – Prior to this amendment, members of the Capitol Police were required to retire either at age 57 or, if older than 57, upon completing 20 years of service. A previous waiver enabled officers to continue working until age 60. This bill increases the retirement age to between ages 57 and 62, when such a waiver is in the public interest. The bipartisan bill was introduced by Sen. Mitch McConnell (R-KY) on May 14. It passed in the Senate on May 15, the House on May 19, and became law on May 29.
American Access to Banking Act (HR 4544) – This law is designed to increase the number of community banks by making it easier to start them. Introduced by Rep. Maxine Waters (D-CA) on July 17, 2025, it passed 405-4 in the House on May 20 and is currently under consideration in the Senate.
Community Bank Deposit Access Act of 2025 (HR 5317) – This bill would create exemptions to FDIC rules that allow banks greater flexibility in funding loans. Specifically, the Act would alter how certain types of deposits are treated so they are no longer classified as brokered deposits. The legislation was introduced by Rep. French Hill (R-AR) on Sept. 11, 2025. It passed in the House on May 20 and currently resides in the Senate.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
For two decades, enterprise software has been built around a simple assumption: people log into multiple applications to retrieve information, make decisions and complete work. A CRM, a project tracker, a business intelligence…
⏱ 4 min read
For two decades, enterprise software has been built around a simple assumption: people log into multiple applications to retrieve information, make decisions, and complete work. A CRM, a project tracker, a business intelligence dashboard, a support ticketing system, and more. All this is because these applications operate in isolation.
There is a shift whose intention is not eliminating SaaS applications. It’s about eliminating the need to constantly switch between them.
Why Dashboards Existed
Dashboards were built because software couldn’t interpret business intent. Humans had to retrieve, interpret charts, and decide what to do next. While dashboards were designed for human navigation, these static SaaS front ends are being replaced by dynamic, real-time interface synthesis.
The dashboard model worked when companies relied on a handful of applications. Today, enterprises manage hundreds of SaaS tools. An average large enterprise runs multiple SaaS applications – about 291 with large organizations scaling over 400. This makes constant switching a productivity problem rather than convenience.
A Harvard Business Review study revealed that digital workers toggle between different applications and websites about 1,200 times a day. This tool-switching alone costs employees an average of 44 hours per year due to tool fatigue. Meanwhile, most of the enterprise SaaS stack goes completely unused, and this is a weighty business cost.
What is Actually Changing
The shift in business computing is not about adding another dashboard to the stack, but rather usurping its purpose. The enterprise interface is beginning to shift toward intent-native workspaces, reducing the need to navigate traditional dashboards for routine work.
In comes agentic AI, which collapses the decision chain. Instead of opening a chart to figure out what it means, the user states an intent and an agent queries the underlying systems directly, synthesizes across them, and gives the user an answer or takes the action itself. For example, instead of a user logging into five different systems, a finance agent pulls real-time vendor invoices from an ERP, a legal agent scans contract terms, and a risk agent cross-references historical delivery delays. All coordinated by an orchestration layer.
Generative user interface (GenUI) technology pairs with this orchestration. Instead of presenting the same dashboard to everyone, a GenUI system generates a temporary interface tailored to the user’s immediate request. Once the task is complete, that interface disappears. If a user inputs their intention, such as checking which supplier poses a risk, the system dynamically renders a clean, interactive panel showing only the relevant vendor risk scores.
A survey by CrewAI on 2026 State of Agentic AI Survey found that adoption of agentic AI is moving fast. Of the 500 senior enterprise executives surveyed, 65 percent are already using AI agents, 81 percent have fully adopted and are actively scaling, and 100 percent plan to expand agentic AI use in 2026.
What Still Matters
Dashboards aren’t disappearing; their role is changing. The shift is not toward a better dashboard; it is to create systems that decide and act directly, with humans overseeing outcomes and not every step. Modern AI-driven operations demand speed that previous tools can’t cope with. Having insights without action is now a bottleneck. Static views, manual interpretation, and the lack of proactive alerts and personalized framing are limitations that drive the shift toward agents.
However, while agentic AI determines what happens next, the dashboards will keep documenting the process. They will also exist mainly as audit trails and compliance records, but not as the primary way work gets done.
What This Means for Your Business
For businesses evaluating software, appearance is becoming less important than accessibility. A polished dashboard matters little if AI agents can’t access its data or trigger actions. As enterprises increasingly rely on AI agents to automate work across multiple systems, software without strong AI integration risks becoming difficult to use, costly to upgrade, and easier to replace.
Logistically, this means businesses should start auditing their software stack for API maturity and AI agent readiness. Before renewing or purchasing new software contracts, a business should evaluate whether the platform has robust APIs, allows AI agents to securely access its data and perform actions, and is built to support an AI-driven workflow.
Conclusion
The biggest disruption is not the end of SaaS dashboards – it’s the end of software that waits for human input. The next generation of enterprise software won’t compete on who has the prettiest dashboard. It will compete on which platform gives AI agents the fastest, safest access to data and actions. Businesses that continue buying interfaces instead of intelligent access may soon find themselves paying for software no one opens.
The Death of the App: Why Your Business Will Sideline SaaS Dashboards
August 1, 2026 · Blog, Uncategorized, What’s New in Technology
⏱ 4 min read
For two decades, enterprise software has been built around a simple assumption: people log into multiple applications to retrieve information, make decisions, and complete work. A CRM, a project tracker, a business intelligence dashboard, a support ticketing system, and more. All this is because these applications operate in isolation.
There is a shift whose intention is not eliminating SaaS applications. It’s about eliminating the need to constantly switch between them.
Why Dashboards Existed
Dashboards were built because software couldn’t interpret business intent. Humans had to retrieve, interpret charts, and decide what to do next. While dashboards were designed for human navigation, these static SaaS front ends are being replaced by dynamic, real-time interface synthesis.
The dashboard model worked when companies relied on a handful of applications. Today, enterprises manage hundreds of SaaS tools. An average large enterprise runs multiple SaaS applications – about 291 with large organizations scaling over 400. This makes constant switching a productivity problem rather than convenience.
A Harvard Business Review study revealed that digital workers toggle between different applications and websites about 1,200 times a day. This tool-switching alone costs employees an average of 44 hours per year due to tool fatigue. Meanwhile, most of the enterprise SaaS stack goes completely unused, and this is a weighty business cost.
What is Actually Changing
The shift in business computing is not about adding another dashboard to the stack, but rather usurping its purpose. The enterprise interface is beginning to shift toward intent-native workspaces, reducing the need to navigate traditional dashboards for routine work.
In comes agentic AI, which collapses the decision chain. Instead of opening a chart to figure out what it means, the user states an intent and an agent queries the underlying systems directly, synthesizes across them, and gives the user an answer or takes the action itself. For example, instead of a user logging into five different systems, a finance agent pulls real-time vendor invoices from an ERP, a legal agent scans contract terms, and a risk agent cross-references historical delivery delays. All coordinated by an orchestration layer.
Generative user interface (GenUI) technology pairs with this orchestration. Instead of presenting the same dashboard to everyone, a GenUI system generates a temporary interface tailored to the user’s immediate request. Once the task is complete, that interface disappears. If a user inputs their intention, such as checking which supplier poses a risk, the system dynamically renders a clean, interactive panel showing only the relevant vendor risk scores.
A survey by CrewAI on 2026 State of Agentic AI Survey found that adoption of agentic AI is moving fast. Of the 500 senior enterprise executives surveyed, 65 percent are already using AI agents, 81 percent have fully adopted and are actively scaling, and 100 percent plan to expand agentic AI use in 2026.
What Still Matters
Dashboards aren’t disappearing; their role is changing. The shift is not toward a better dashboard; it is to create systems that decide and act directly, with humans overseeing outcomes and not every step. Modern AI-driven operations demand speed that previous tools can’t cope with. Having insights without action is now a bottleneck. Static views, manual interpretation, and the lack of proactive alerts and personalized framing are limitations that drive the shift toward agents.
However, while agentic AI determines what happens next, the dashboards will keep documenting the process. They will also exist mainly as audit trails and compliance records, but not as the primary way work gets done.
What This Means for Your Business
For businesses evaluating software, appearance is becoming less important than accessibility. A polished dashboard matters little if AI agents can’t access its data or trigger actions. As enterprises increasingly rely on AI agents to automate work across multiple systems, software without strong AI integration risks becoming difficult to use, costly to upgrade, and easier to replace.
Logistically, this means businesses should start auditing their software stack for API maturity and AI agent readiness. Before renewing or purchasing new software contracts, a business should evaluate whether the platform has robust APIs, allows AI agents to securely access its data and perform actions, and is built to support an AI-driven workflow.
Conclusion
The biggest disruption is not the end of SaaS dashboards – it’s the end of software that waits for human input. The next generation of enterprise software won’t compete on who has the prettiest dashboard. It will compete on which platform gives AI agents the fastest, safest access to data and actions. Businesses that continue buying interfaces instead of intelligent access may soon find themselves paying for software no one opens.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Surprising at it may seem, Q4 is at your doorstep, knocking and asking for attention. What’s more, it’s that time of year when everything starts getting busy: kids go back to school, football starts…
⏱ 4 min read
Surprising as it may seem, Q4 is at your doorstep, knocking and asking for attention. What’s more, it’s that time of year when everything starts getting busy: kids go back to school, football starts, and then the holidays are just up ahead. During this time, you might also be hearing “cha-ching, cha-ching” as what lies ahead can be financially challenging. Consider a few ways to frame this and strategies to set up goals as you bring the year to a close.
Map out the big picture. While all the things in your immediate future might be at the forefront of your mind, take a step back. What’s your five-year vision? Where are you with your big life goals? Do they include saving for a down payment for a house, a dream vacay, or setting up a college fund for your kids? Decide on completion dates and work backward. What needs to happen for these things to become realities?
Focus on the next 90 days. Now you can get a bit more granular. What’s looming in the future, before the year ends? What are your holiday plans? Usually this involves expenses (travel and food). Brainstorm about how to economize. Can you cost-share with family and friends? (Thinking here about your five-year vision.) What about your home and cars? Do they need work, and what might you spend? Do you have an emergency fund to help with all this? If you don’t, start one! Keep all of these things in mind as you make your way toward next year and beyond.
Set up a tracker. It can be an Excel spreadsheet, a notebook, or a whiteboard – whatever works for you. Color code different milestones and then brainstorm (yes, again) to see how you can reach these goals. Do you need to cut expenses in some areas? Pick up a side hustle? Purge your closet (house, too), and sell some things? To get started, here are a few tracker templates to kick things off.
Create SMART goals. You might have heard of this acronym, but it stands for:
Specific: Needs to be concrete, not vague.
Measurable: Must be specific dollar amounts.
Attainable: Within your budget but still challenging.
Relevant: Aligned with your five-year goals, your future dreams.
Time-bound: Hard deadlines.
Separate your goals into buckets. Those would be long-, medium-, and short-term.
Long-term: This is 5-plus years. Early retirement by XX years old with a specific amount of money in the bank. Paying off your house by a certain date. Having a certain amount of cash saved for your kiddos after you’re gone.
Medium-term: This is 1-5 years. The usual suspects include paying off your car, student loans, consumer debt, or even building up a (dollar amount goes here) reserve for a down payment on a house or second property.
Short-term goals and quarterly goals: This is less than 1 year – hot items you cannot ignore. Starting, or adding to, your emergency fund that will equal, let’s say, $5,000. Or, for instance, saving $8,000 for a family vacation. You can also look at these small goals as subsets of larger goals: paying off X% of your house or car note by a certain date.
In sum, all of the above are simple ways to wrap your head around how to navigate Q4 financial goals – and beyond – by carving them up into smaller, digestible steps. If you can get organized, take on the last half of the year with intention, and make some real progress, there’s nothing in the (fiscal) world you can’t accomplish if you set your mind to it.
August 1, 2026 · Blog, Tip of the Month, Uncategorized
⏱ 4 min read
Surprising as it may seem, Q4 is at your doorstep, knocking and asking for attention. What’s more, it’s that time of year when everything starts getting busy: kids go back to school, football starts, and then the holidays are just up ahead. During this time, you might also be hearing “cha-ching, cha-ching” as what lies ahead can be financially challenging. Consider a few ways to frame this and strategies to set up goals as you bring the year to a close.
Map out the big picture. While all the things in your immediate future might be at the forefront of your mind, take a step back. What’s your five-year vision? Where are you with your big life goals? Do they include saving for a down payment for a house, a dream vacay, or setting up a college fund for your kids? Decide on completion dates and work backward. What needs to happen for these things to become realities?
Focus on the next 90 days. Now you can get a bit more granular. What’s looming in the future, before the year ends? What are your holiday plans? Usually this involves expenses (travel and food). Brainstorm about how to economize. Can you cost-share with family and friends? (Thinking here about your five-year vision.) What about your home and cars? Do they need work, and what might you spend? Do you have an emergency fund to help with all this? If you don’t, start one! Keep all of these things in mind as you make your way toward next year and beyond.
Set up a tracker. It can be an Excel spreadsheet, a notebook, or a whiteboard – whatever works for you. Color code different milestones and then brainstorm (yes, again) to see how you can reach these goals. Do you need to cut expenses in some areas? Pick up a side hustle? Purge your closet (house, too), and sell some things? To get started, here are a few tracker templates to kick things off.
Create SMART goals. You might have heard of this acronym, but it stands for:
Specific: Needs to be concrete, not vague.
Measurable: Must be specific dollar amounts.
Attainable: Within your budget but still challenging.
Relevant: Aligned with your five-year goals, your future dreams.
Time-bound: Hard deadlines.
Separate your goals into buckets. Those would be long-, medium-, and short-term.
Long-term: This is 5-plus years. Early retirement by XX years old with a specific amount of money in the bank. Paying off your house by a certain date. Having a certain amount of cash saved for your kiddos after you’re gone.
Medium-term: This is 1-5 years. The usual suspects include paying off your car, student loans, consumer debt, or even building up a (dollar amount goes here) reserve for a down payment on a house or second property.
Short-term goals and quarterly goals: This is less than 1 year – hot items you cannot ignore. Starting, or adding to, your emergency fund that will equal, let’s say, $5,000. Or, for instance, saving $8,000 for a family vacation. You can also look at these small goals as subsets of larger goals: paying off X% of your house or car note by a certain date.
In sum, all of the above are simple ways to wrap your head around how to navigate Q4 financial goals – and beyond – by carving them up into smaller, digestible steps. If you can get organized, take on the last half of the year with intention, and make some real progress, there’s nothing in the (fiscal) world you can’t accomplish if you set your mind to it.
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
No matter how well you know someone, you usually learn a lot more once you’ve traveled with them. We are all different in this activity, from people who prefer aisle seats over window seats, to Airbnb renters or hotel…
⏱ 5 min read
No matter how well you know someone, you usually learn a lot more once you’ve traveled with them. We are all different in this activity, from people who prefer aisle seats over window seats, to Airbnb renters or hotel enthusiasts, to the outdoorsy versus museum aficionados.
Friendship compatibility does not always translate to travel compatibility. Therefore, before you load up the car or board public transportation, it will help to communicate preferences, establish a few ground rules, and, perhaps most importantly, decide how to share expenses.
There are plenty of advantages to traveling with another person or a group of people, even if you tend to be a loner. For example, sharing expenses for accommodations, a car rental, or even a bottle of wine over dinner can cut your vacation budget substantially. However, if you don’t have a plan for what expenses to share and how to track them, you may return home short-changed, resentful, and with one less person in your life.
Ground Rules
It’s important to gauge upfront if everyone is on the same page as to how much money they want to spend on the trip, and even establish a maximum budget so no one gets trapped into paying more than they can afford. This means determining the level of accommodations (e.g., luxury versus budget-friendly) to shop for, whether or not you want the option to cook meals as opposed to eating out all the time, and the main activities the group plans to engage in (e.g., free hiking versus expensive snow skiing). Establish what types of expenses will be shared, such as group meals, housing and car rental, and what will be paid for individually, such as airfare, solo outings and souvenirs.
Choose Your Tracking Method
There are two approaches for sharing the expenses of travel: Wing it or track it. Winging implies a more casual tactic. For example, one person picks up the hotel room tab, another pays for the rental car, another pays for meals. Perhaps you rotate or take turns picking up comparable bills. The goal is to generally spread expenses evenly across all payers, but winging it may lead to one (or more) travelers paying more while the other(s) pay less. If everyone agrees their outlays may differ, then this tactic will probably work just fine.
Tracking Tools
The second approach is to track all shared expenses with some degree of accuracy. This is easier if all expenses are shared evenly, but more complex if expenses need to be broken down into who ordered a salad and who ordered the filet mignon.
Fortunately, there is a plethora of electronic technologies and digital tools designed to make it easier to track travel expenses and ensure no one overpays – right down to the penny.
PayPal, Venmo, Zelle – These services make it easy to send or request money using apps. They may require travelers to keep receipts and calculate individual tabs, then settle up at the end of the day or the end of the trip. This tactic can be a little unwieldy, and may require manual tracking to ensure no one is paying too much or too little along the way. All travelers should sign up for at least one compatible money transfer app; they are generally free to use.
Splitwise – This app enables participants in a travel group to enter the expenses they paid by adding the names of the participants and breaking down the individual amounts each person contributed to each bill. The app tracks expenses by person, then tallies up who owes money at the end. Splitwise calculates who owes whom. Travelers can then settle balances using their preferred payment method, such as PayPal, Venmo, Zelle, bank transfer, cash, or another supported payment service. Splitwise is just one brand name of many apps that work similarly, including Tricount and Revolut.
Cino – This app works a bit differently in that each traveler links it to their personal credit or debit card, and the group Cino card is loaded into Apple Pay or Google Pay. Then all participants share a virtual card to pay for expenses, which divides each payment at the point of purchase among the participants for that expense. When one person pays for an expense, everyone’s share is automatically charged to each member’s connected credit or debit account. Note that Cino does not break down invoices by line item to track exactly who ate what; it follows a split ratio (e.g., 50%-50%) as determined up front by the group.
Artificial Intelligence – Travelers may want to give AI a try, where as they start with a prompt asking the service to track and split group expenses, then enter the names of participants and related expenses to the prompt on an ongoing basis. AI tools can organize, categorize, and calculate shared expenses that users enter manually. Some AI assistants may also summarize spending trends or generate settlement calculations, but they generally do not automatically track purchases unless integrated with financial apps.
Given today’s higher prices, group travel is becoming more prevalent as a way to share the cost of vacation. According to a 2025 Zeta Global survey, 40 percent of travelers are going on trips with family while 21 percent opt to vacation with friends. Today’s new digital tools make it easy to track and share expenses so that you don’t strain relationships with travel companions.
Travel Companions: How to Share Expenses
August 1, 2026 · Blog, Financial Planning, Uncategorized
⏱ 5 min read
No matter how well you know someone, you usually learn a lot more once you’ve traveled with them. We are all different in this activity, from people who prefer aisle seats over window seats, to Airbnb renters or hotel enthusiasts, to the outdoorsy versus museum aficionados.
Friendship compatibility does not always translate to travel compatibility. Therefore, before you load up the car or board public transportation, it will help to communicate preferences, establish a few ground rules, and, perhaps most importantly, decide how to share expenses.
There are plenty of advantages to traveling with another person or a group of people, even if you tend to be a loner. For example, sharing expenses for accommodations, a car rental, or even a bottle of wine over dinner can cut your vacation budget substantially. However, if you don’t have a plan for what expenses to share and how to track them, you may return home short-changed, resentful, and with one less person in your life.
Ground Rules
It’s important to gauge upfront if everyone is on the same page as to how much money they want to spend on the trip, and even establish a maximum budget so no one gets trapped into paying more than they can afford. This means determining the level of accommodations (e.g., luxury versus budget-friendly) to shop for, whether or not you want the option to cook meals as opposed to eating out all the time, and the main activities the group plans to engage in (e.g., free hiking versus expensive snow skiing). Establish what types of expenses will be shared, such as group meals, housing and car rental, and what will be paid for individually, such as airfare, solo outings and souvenirs.
Choose Your Tracking Method
There are two approaches for sharing the expenses of travel: Wing it or track it. Winging implies a more casual tactic. For example, one person picks up the hotel room tab, another pays for the rental car, another pays for meals. Perhaps you rotate or take turns picking up comparable bills. The goal is to generally spread expenses evenly across all payers, but winging it may lead to one (or more) travelers paying more while the other(s) pay less. If everyone agrees their outlays may differ, then this tactic will probably work just fine.
Tracking Tools
The second approach is to track all shared expenses with some degree of accuracy. This is easier if all expenses are shared evenly, but more complex if expenses need to be broken down into who ordered a salad and who ordered the filet mignon.
Fortunately, there is a plethora of electronic technologies and digital tools designed to make it easier to track travel expenses and ensure no one overpays – right down to the penny.
PayPal, Venmo, Zelle – These services make it easy to send or request money using apps. They may require travelers to keep receipts and calculate individual tabs, then settle up at the end of the day or the end of the trip. This tactic can be a little unwieldy, and may require manual tracking to ensure no one is paying too much or too little along the way. All travelers should sign up for at least one compatible money transfer app; they are generally free to use.
Splitwise – This app enables participants in a travel group to enter the expenses they paid by adding the names of the participants and breaking down the individual amounts each person contributed to each bill. The app tracks expenses by person, then tallies up who owes money at the end. Splitwise calculates who owes whom. Travelers can then settle balances using their preferred payment method, such as PayPal, Venmo, Zelle, bank transfer, cash, or another supported payment service. Splitwise is just one brand name of many apps that work similarly, including Tricount and Revolut.
Cino – This app works a bit differently in that each traveler links it to their personal credit or debit card, and the group Cino card is loaded into Apple Pay or Google Pay. Then all participants share a virtual card to pay for expenses, which divides each payment at the point of purchase among the participants for that expense. When one person pays for an expense, everyone’s share is automatically charged to each member’s connected credit or debit account. Note that Cino does not break down invoices by line item to track exactly who ate what; it follows a split ratio (e.g., 50%-50%) as determined up front by the group.
Artificial Intelligence – Travelers may want to give AI a try, where as they start with a prompt asking the service to track and split group expenses, then enter the names of participants and related expenses to the prompt on an ongoing basis. AI tools can organize, categorize, and calculate shared expenses that users enter manually. Some AI assistants may also summarize spending trends or generate settlement calculations, but they generally do not automatically track purchases unless integrated with financial apps.
Given today’s higher prices, group travel is becoming more prevalent as a way to share the cost of vacation. According to a 2025 Zeta Global survey, 40 percent of travelers are going on trips with family while 21 percent opt to vacation with friends. Today’s new digital tools make it easy to track and share expenses so that you don’t strain relationships with travel companions.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
With more than $57 trillion in mergers and acquisitions, according to the Institute for Mergers, Acquisitions & Alliances, understanding…
⏱ 3 min read
With more than $57 trillion in mergers and acquisitions, according to the Institute for Mergers, Acquisitions & Alliances, understanding how the Exchange Ratio works is essential for businesses and investors to maximize these processes.
The ratio assesses how many shares the company that’s purchasing the takeover company must issue per share of the takeover business. Transactions that use shares for part or whole of the payment are able to leverage this integral benchmark. It’s important to keep in mind that the exchange ratio may provide parties helpful insight on transactions involving all or part equity, but it won’t be beneficial for all cash deals.
The formula to calculate the ratio is as follows:
Exchange Ratio = Offer Price for Target’s Shares / Acquirer’s Share Price
Looking at the acquiring firm’s and the target or acquired firm’s share prices illustrates the exchange ratio. If the target firm has 30,000 shares outstanding and trades at $34.60, and the acquiring firm offers to pay a 20 percent takeover, it results in a share price of $41.52 per share. The acquiring firm’s share price currently trades at $23.50.
Putting the formula into practice, it’s as follows:
= $41.52 / $23.50
= 1.77
Based on the resulting Exchange Ratio of 1.77, the acquiring firm must issue 1.77 shares of its equity for each share of the target firm it wants to acquire.
For transactions with different proportions of cash and stock, the percentage of stock is what’s factored into the exchange ratio. Deals conducted with 100 percent stock provide the most value to an exchange ratio.
Real World Example
If an acquiring business offers the acquisition target two of its shares for a single share of the acquired company, the deal can take the following circumstances. Before the deal announcement, the purchasing company’s shares might be trading at $20, with the target company’s shares trading at $30. With a 2-to-1 exchange ratio, the purchaser is bidding $40 for the seller’s share at $30.
After the deal announcement, there’s usually a valuation difference between buyer and seller due to the time value of money and risks. Risks include potentially being blocked by regulators, shareholder rejection or changing economic conditions. One important consideration is that merger arbitration may occur by investors when they try to get ahead of a deal ultimately completing before the uncertainty is removed.
If the deal ultimately closes, and investors get two buyer shares in exchange for one seller share and the acquiring company’s share increases to $37 from $30, investors who bet against the buyer’s stock via short-selling will be rewarded a difference of $3 per share (2 shares from the acquiring company 2 X $20 = $40 minus the $37 single share price of the target company). Investors who close out their short position will see the difference from the seller’s price for a profit. This tactic is frequently executed by opportunistic investors who have no direct interest in owning the equity, but only for a trade.
While each deal is different, understanding the process is essential to break down the internal details for all interested merger and acquisition parties.
Understanding the Exchange Ratio
August 1, 2026 · Blog, General Business News, Uncategorized
⏱ 3 min read
With more than $57 trillion in mergers and acquisitions, according to the Institute for Mergers, Acquisitions & Alliances, understanding how the Exchange Ratio works is essential for businesses and investors to maximize these processes.
The ratio assesses how many shares the company that’s purchasing the takeover company must issue per share of the takeover business. Transactions that use shares for part or whole of the payment are able to leverage this integral benchmark. It’s important to keep in mind that the exchange ratio may provide parties helpful insight on transactions involving all or part equity, but it won’t be beneficial for all cash deals.
The formula to calculate the ratio is as follows:
Exchange Ratio = Offer Price for Target’s Shares / Acquirer’s Share Price
Looking at the acquiring firm’s and the target or acquired firm’s share prices illustrates the exchange ratio. If the target firm has 30,000 shares outstanding and trades at $34.60, and the acquiring firm offers to pay a 20 percent takeover, it results in a share price of $41.52 per share. The acquiring firm’s share price currently trades at $23.50.
Putting the formula into practice, it’s as follows:
= $41.52 / $23.50
= 1.77
Based on the resulting Exchange Ratio of 1.77, the acquiring firm must issue 1.77 shares of its equity for each share of the target firm it wants to acquire.
For transactions with different proportions of cash and stock, the percentage of stock is what’s factored into the exchange ratio. Deals conducted with 100 percent stock provide the most value to an exchange ratio.
Real World Example
If an acquiring business offers the acquisition target two of its shares for a single share of the acquired company, the deal can take the following circumstances. Before the deal announcement, the purchasing company’s shares might be trading at $20, with the target company’s shares trading at $30. With a 2-to-1 exchange ratio, the purchaser is bidding $40 for the seller’s share at $30.
After the deal announcement, there’s usually a valuation difference between buyer and seller due to the time value of money and risks. Risks include potentially being blocked by regulators, shareholder rejection or changing economic conditions. One important consideration is that merger arbitration may occur by investors when they try to get ahead of a deal ultimately completing before the uncertainty is removed.
If the deal ultimately closes, and investors get two buyer shares in exchange for one seller share and the acquiring company’s share increases to $37 from $30, investors who bet against the buyer’s stock via short-selling will be rewarded a difference of $3 per share (2 shares from the acquiring company 2 X $20 = $40 minus the $37 single share price of the target company). Investors who close out their short position will see the difference from the seller’s price for a profit. This tactic is frequently executed by opportunistic investors who have no direct interest in owning the equity, but only for a trade.
While each deal is different, understanding the process is essential to break down the internal details for all interested merger and acquisition parties.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
 Temps are dropping, the leaves are turning, and you know what that means: Fall is here, which is the best time to prepare your house for the chill that follows. But we all know that keeping warm takes energy and, yes, is costly. Here are a few easy ways to conserve.



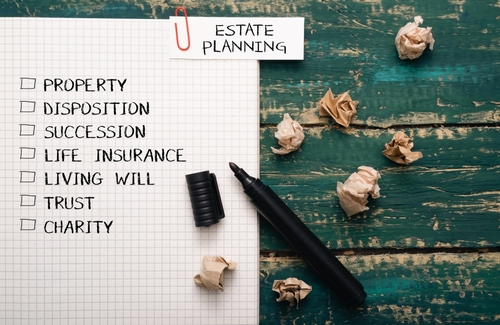 The purpose of estate planning is to distribute your assets to heirs in a formal, legal process. If you do not have any heirs to speak of, you might not feel the need to do this. However, your assets will go somewhere, so you may want to have control over that before the state steps in to decide for you.
 According to Fitch Ratings, over the past 12 months ending August 2026, there were 109 defaults by 89 entities, compared to the same period ending July 2026, when 83 entities saw 105 defaults. With businesses (especially life insurers) exposed to asset management risks, it’s important to understand how to find financial balance.
 Anyone who has moved retirement money out of an old employer’s plan knows how frustrating it can be. Every administrator has their own forms. Timelines are all over the place. Paper checks show up weeks later with vague instructions. The whole thing should have been fixed a long time ago.
 With over $4 trillion in merger and acquisition transactions happening in 2025, understanding the necessary accounting considerations is essential to see how tax professionals can navigate financial statements.
 Sunshine Protection Act of 2025 (HR 139) – The purpose of this legislation is to make daylight savings time (DST) permanent for most of the country. States and territories presently exempt from DST may choose the standard time for those areas. This latest version of the bill was introduced by Rep. Vern Buchanan (R-FL) on Jan. 3, 2025. The Act passed in the House on July 14 and faces a mix of cross-aisle opposition and support in the Senate.
 For two decades, enterprise software has been built around a simple assumption: people log into multiple applications to retrieve information, make decisions, and complete work. A CRM, a project tracker, a business intelligence dashboard, a support ticketing system, and more. All this is because these applications operate in isolation.
 Surprising as it may seem, Q4 is at your doorstep, knocking and asking for attention. What’s more, it’s that time of year when everything starts getting busy: kids go back to school, football starts, and then the holidays are just up ahead. During this time, you might also be hearing “cha-ching, cha-ching” as what lies ahead can be financially challenging. Consider a few ways to frame this and strategies to set up goals as you bring the year to a close.
 No matter how well you know someone, you usually learn a lot more once you’ve traveled with them. We are all different in this activity, from people who prefer aisle seats over window seats, to Airbnb renters or hotel enthusiasts, to the outdoorsy versus museum aficionados.
 With more than $57 trillion in mergers and acquisitions, according to the